Stablecoins are the part of crypto that is designed not to move. Bitcoin can swing 10% in a day; a stablecoin is built to stay at one dollar, one euro or one ounce of gold. That makes them the working currency of the crypto economy: traders park in them between positions, people abroad use them to hold dollars their banks will not give them, and lenders use them as collateral and settlement. But "stablecoin" covers several very different designs, and the design decides how safe your money actually is.
This article explains what a stablecoin is, the four main types, what each is used for, and where each has failed.
What is a stablecoin?
A stablecoin is a digital currency that aims to reduce price fluctuations. It combines the benefits of cryptocurrency, such as fast global transfers and self-custody, with the goal of minimising volatility.
Stablecoins are often used as a reliable store of value in the crypto market. They are designed to hold their value consistently, unlike Bitcoin, which can experience extreme volatility. They stay stable by being tied to a reserve asset like US dollars or gold, or by a mechanism that adjusts supply to hold the price.
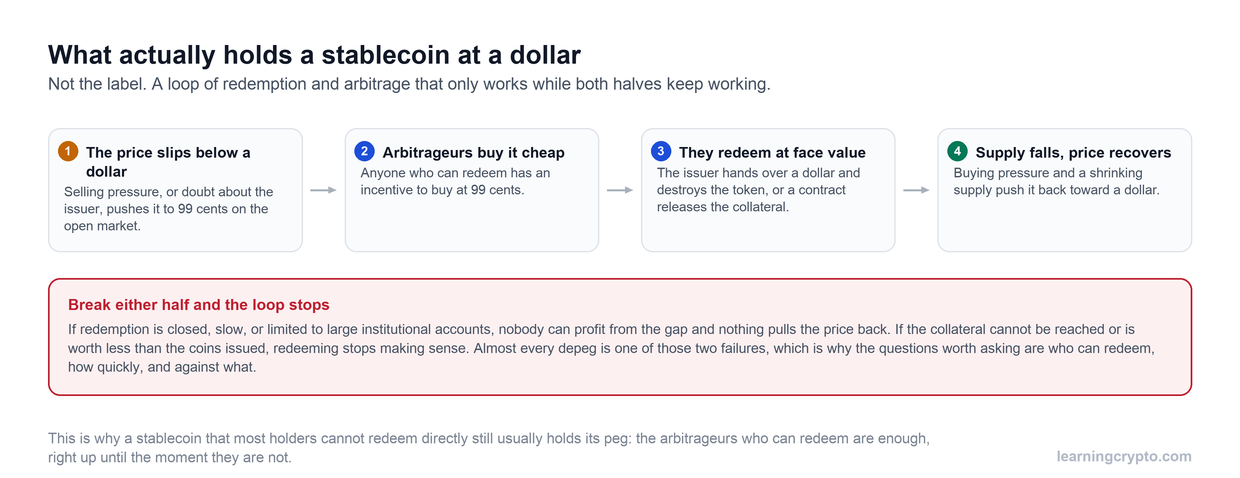
Stablecoin definition: a cryptocurrency that aims to maintain a stable value by being backed by a reserve of assets. This makes it useful for transactions, savings, and as a stable medium of exchange in the cryptocurrency market. If you want the mechanics of how a coin holds its target price, our explainer on what pegging means in crypto goes into detail.
What are the different types of stablecoins?
There are four main types, and the cleanest way to tell them apart is to ask what backs the coin: dollars in a bank, crypto locked in a smart contract, a physical commodity in a vault, or nothing but an algorithm. The first three hold up in a crisis to different degrees. The fourth has a poor record.
1. Fiat-collateralized stablecoins
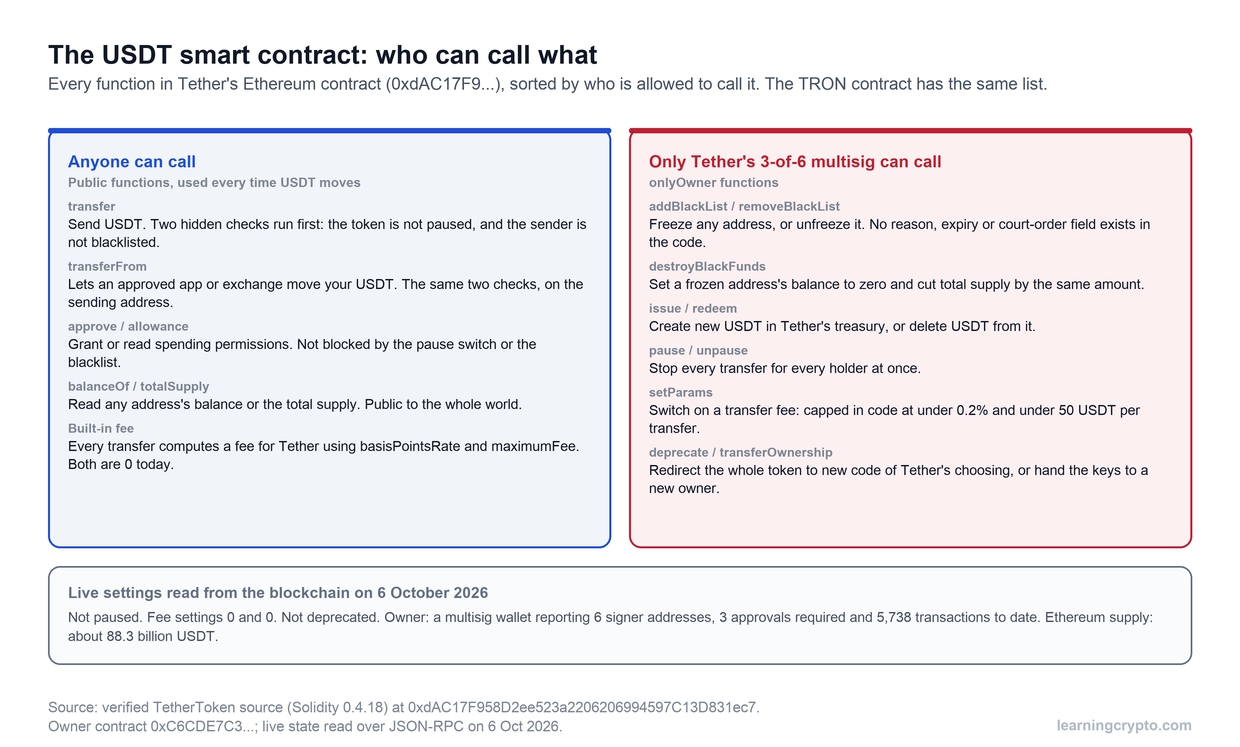
These are backed one-to-one by real-world currency held by a company. Tether (USDT) and USD Coin (USDC) are the largest and make up the vast majority of the stablecoin market. The issuer holds cash and short-term US Treasury bills and publishes attestations of its reserves. You trust the issuer, its banks and its auditors, and the issuer can freeze addresses when ordered to. In return, these coins are the most liquid and the easiest to cash out, and since the 2025 GENIUS Act the US has a federal rulebook for how they must be backed. Our USDT vs USDC comparison covers the reserve and risk differences between the two big names.
2. Crypto-collateralized stablecoins
These are backed by other cryptocurrencies locked in smart contracts, with no company holding your dollars. DAI from MakerDAO (now also issued as USDS under the Sky brand) is the best-known example. Because the collateral is volatile, the system over-collateralizes: you might lock $150 of ETH to mint $100 of DAI, and if the collateral value falls too far it is automatically sold to protect the peg. The reserves are visible on-chain at any moment, which is a genuine advantage. The risk is a sudden crash that overwhelms the liquidation system.
3. Commodity-backed stablecoins
These track a physical asset rather than a currency. Pax Gold (PAXG) and Tether Gold (XAUT) each represent one troy ounce of gold held in a vault, so the token's price moves with gold, not the dollar. They suit people who want gold exposure they can move at internet speed, and they are "stable" only relative to crypto, since gold itself moves. Redemption for physical metal usually has high minimums and fees.
4. Algorithmic stablecoins
These hold their peg with code alone, expanding and contracting supply, often paired with a second volatile token that absorbs the swings. The design is elegant on paper and has failed repeatedly in practice. TerraUSD (UST) was the largest, and in May 2022 it lost its peg and collapsed along with its sister token LUNA, wiping out roughly $40 billion in a week. Any coin that promises stability without real reserves deserves deep scepticism.
What are stablecoins used for?
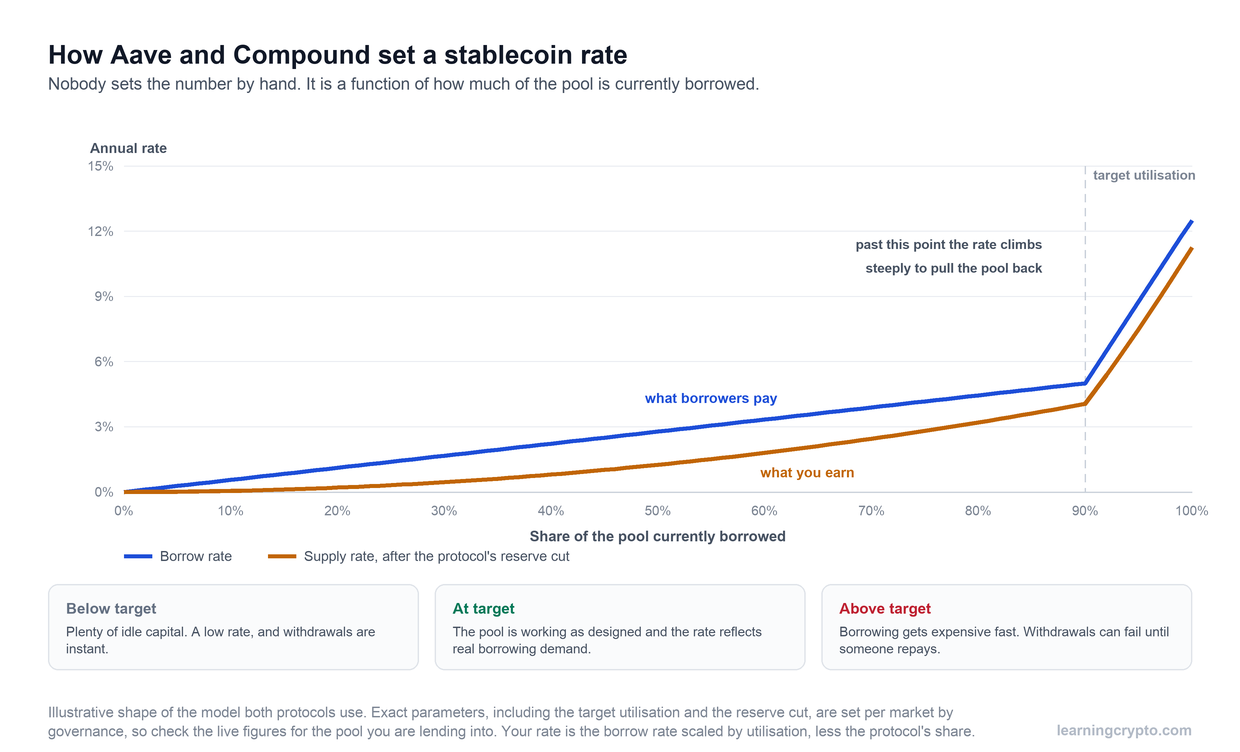
Trading is the biggest use: exchanges quote most pairs against USDT or USDC, and moving to a stablecoin is how traders step out of the market without touching a bank. Savings and dollar access come next, especially in countries with weak currencies or capital controls. Payments and remittances are growing because a transfer settles in minutes for cents. In decentralised finance, stablecoins are the main collateral and lending asset, which is where yield-bearing stablecoins and lending interest come from.
Which type of stablecoin should you use?
For most people, a large fiat-backed coin from a regulated issuer is the sensible default because it is the most liquid and the simplest to understand. If you object to a company being able to freeze funds, a crypto-collateralized coin like DAI trades that control for on-chain transparency. Gold-backed tokens are a different product for a different goal. Avoid purely algorithmic coins.
Whichever you choose, a stablecoin is a claim on someone's reserves, not the reserve itself, and it is not insured like a bank deposit. Even USDC briefly traded below $0.90 in March 2023 when one of its banks failed. If you are weighing a stablecoin against simply holding Bitcoin, our stablecoins vs Bitcoin guide lays out the trade-offs, and our stablecoins hub collects everything we have written on the subject. If you have a specific coin in mind and want a plain-English risk read, you can ask Ask Crypto directly.
Conclusion
Whether you are a seasoned investor or new to the crypto space, understanding stablecoin types and their benefits helps you move through the market with more confidence.
From fiat-collateralized stablecoins to algorithmic stablecoins, each type offers different advantages and carries different risks, which is why stablecoins are such an essential tool for anyone looking to hold value steady in digital finance.
Want to go deeper into stablecoins and their role in the crypto world? Join our crypto membership for expert insights, exclusive resources, and live Q&A sessions.
FAQ
What is the safest type of stablecoin?
Large fiat-backed coins from regulated issuers that publish regular reserve attestations, such as USDC, have the strongest record for holding their peg and for redemption. Crypto-backed coins like DAI are transparent but depend on volatile collateral. Nothing is risk-free: issuer failure, bank failure and regulatory action can all affect a stablecoin, so avoid keeping more in one coin than you could stand to have frozen.
Can a stablecoin lose its peg?
Yes. Algorithmic coins have collapsed outright, TerraUSD being the largest example. Even well-backed coins can dip temporarily when there is doubt about reserves or when markets panic, as USDC did in March 2023 before recovering within days. A brief dip is different from a permanent failure, but both are reasons to know exactly what backs the coin you hold.
Do stablecoins pay interest?
The coin itself generally does not, and US law now restricts issuers from paying yield directly to holders. Interest comes from lending your stablecoins through an exchange or a DeFi protocol, or from separate yield-bearing tokens that pass through Treasury income. Every one of those routes adds platform or smart-contract risk on top of the stablecoin's own risk.
Are stablecoins the same as a central bank digital currency?
No. Stablecoins are issued by private companies or decentralised protocols and are redeemable for the assets backing them. A CBDC would be a direct liability of a central bank, with the state able to see and control every transaction. They can look similar in a wallet, but the issuer and the degree of control over your funds are very different.